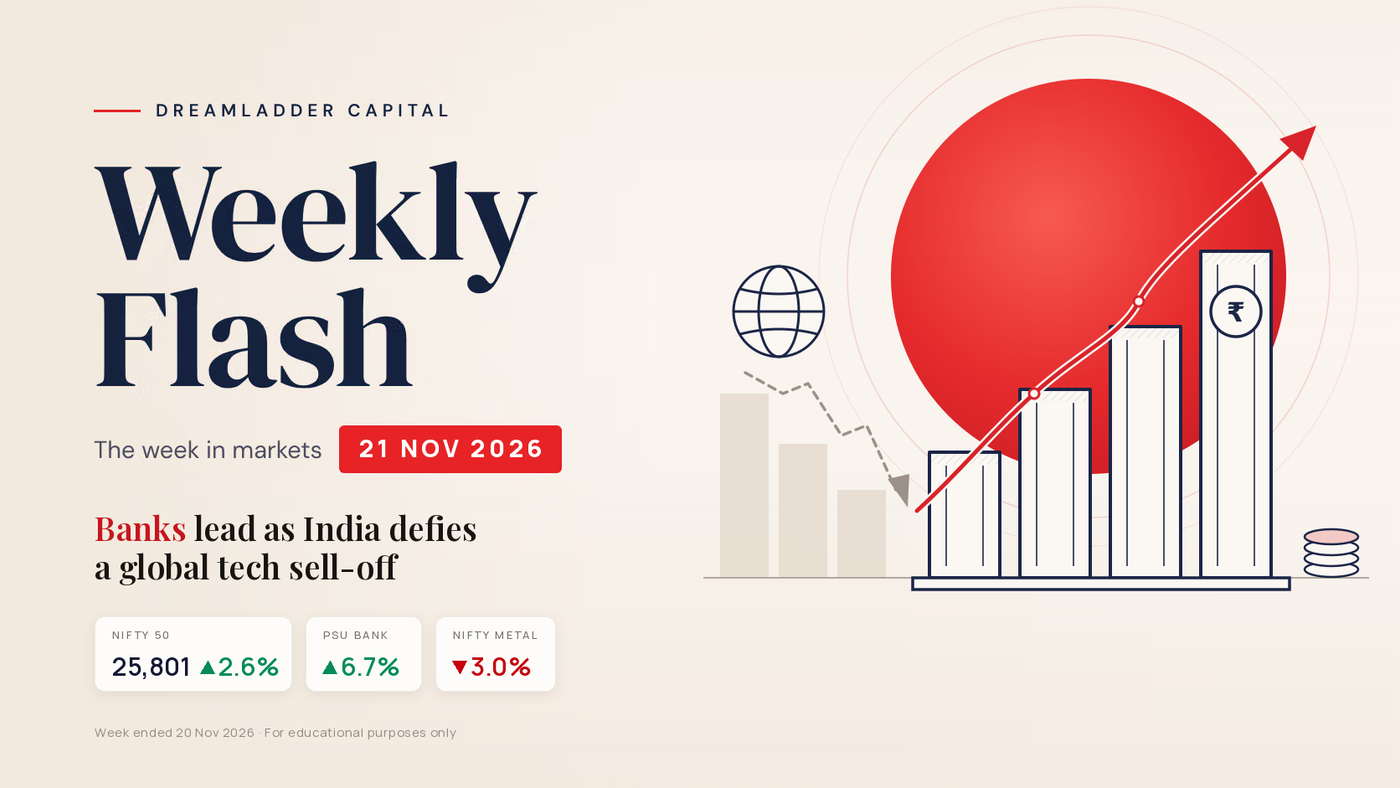
Indian equities rose for a fourth straight week, with the Nifty 50 up 2.6% to 25,801 and the Sensex up 2.9% to 83,920. PSU Banks led the sectoral advance with a 6.7% gain, followed by the broader banking index at 5.9%. FMCG, Consumption and Auto also moved higher, while Metal was the weakest sector, falling 3.0%, followed by IT, which slipped 1.9% as global technology stocks sold off.
Stock-level moves were sharper than the benchmark gains suggest. Max Healthcare (+14%) led the Nifty 50 gainers, followed by Maruti Suzuki and Axis Bank, while Tata Motors Passenger Vehicles, Tata Steel and Titan came under pressure. In the Nifty 500, Deepak Fertilisers, Blue Star and Signature Global gained 13% each, while Kaynes Technology fell 15%. Foreign institutional investors bought roughly ₹32,600 crore of equities on a net basis, more than offsetting domestic institutional selling of about ₹12,700 crore. India has been the largest recipient of foreign inflows among major emerging markets this month, while Taiwan saw heavy outflows.
Global equities fell sharply as concerns over AI valuations and the returns on rising AI spending triggered a broad sell-off. The Nasdaq dropped 10%, the S&P 500 8.6% and the Dow 8.0% for the week. In Asia, Taiwan (-17.5%), Korea and Japan saw the steepest declines, and every tracked overseas market ended lower. Treasury yields eased late in the week as investors moved towards safer assets, while the US Dollar Index rose 0.4% to 103.84 on safe-haven demand.
Metals came under heavy selling. Gold fell 9.5% to about $3,515 an ounce and silver 15.2% to $41.2, as expectations of tighter US monetary policy weighed on precious metals. Copper dropped 10.1% amid the unwinding of AI-related positions and concerns over Chinese demand. Brent crude declined 3.4% to $92.6 a barrel, with strong Middle Eastern exports and expectations of a global supply surplus outweighing supply risks.
The rupee strengthened 1.3% to ₹93.0 per dollar, supported by foreign inflows and softer crude, and India's 10-year bond yield eased to 7.2% from 7.3%. October retail inflation rose to 6.1%, crossing the RBI's 6% upper tolerance limit and keeping inflation in focus ahead of the December policy review. Softer crude and a firmer rupee eased some pressure on import costs.
Q2FY27 results continued to point to an improving earnings cycle. Metals & Mining, Industrials and PSU Banks delivered some of the strongest outcomes, while Internet, Infrastructure and Utilities faced greater pressure. Consensus projects around 15% profit growth in FY27, and the Nifty 50 trades at roughly 21x FY27 and 18x FY28 consensus earnings. Second-half results will show whether demand and operating margins can sustain the first-half recovery.
A sustained advance will depend on whether foreign buying persists, how global technology stocks settle, the US Federal Reserve's December decision and the path of domestic inflation. Continued inflows could help broaden participation beyond banks, while renewed weakness in global markets could test India's recent resilience.
The full Weekly Flash, with sector, stock, global and commodity tables, is available as a PDF below.