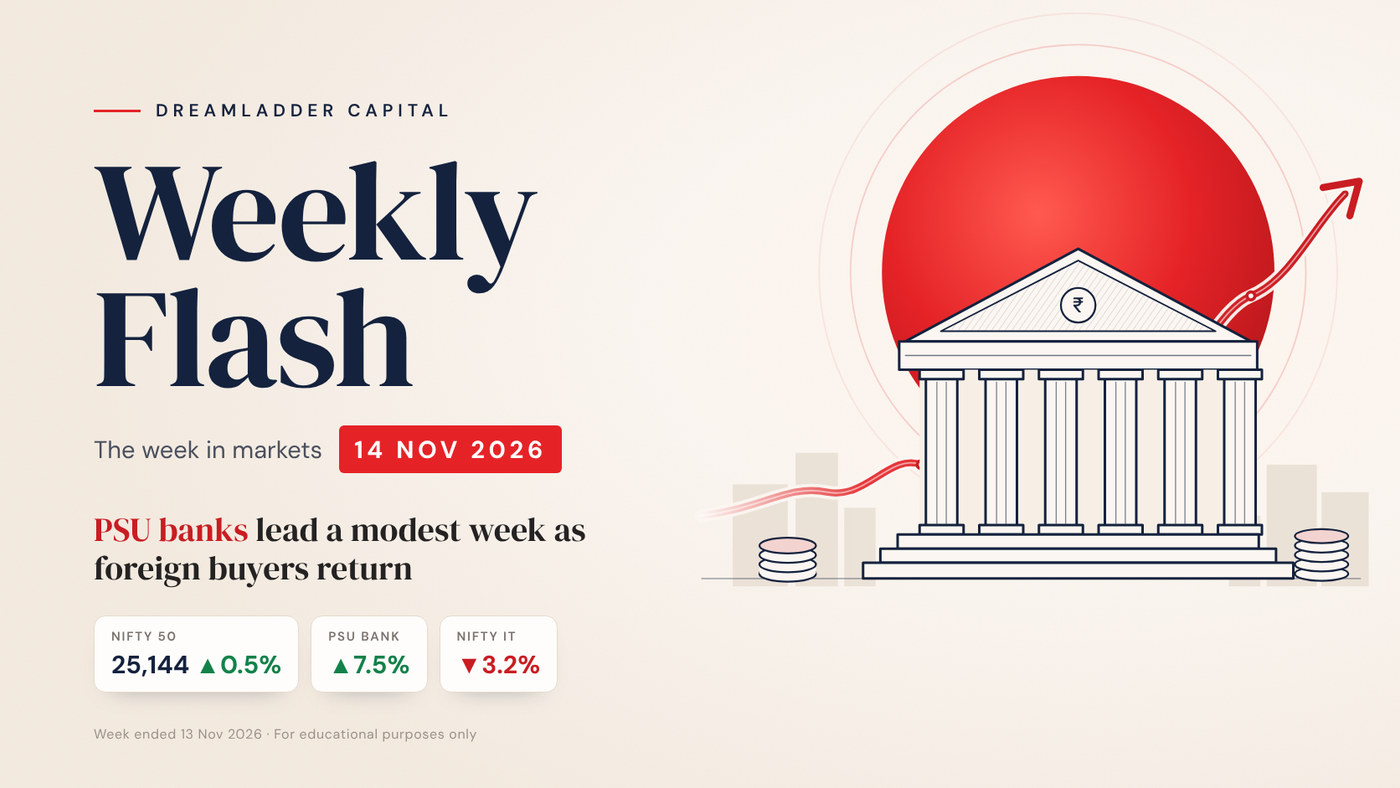
Indian equities ended the week with modest gains, with the Nifty 50 up 0.5% and the Sensex up 0.7%. PSU Banks led the sectoral advance with a 7.5% gain, followed by Media and the broader banking index. Realty and Pharma also moved higher, while IT was the weakest sector, falling 3.2% even as US equities rebounded.
Stock-level moves were more pronounced than the benchmark gains suggest. State Bank of India and HDFC Life led the Nifty 50 gainers, while Grasim and several large IT stocks came under pressure. In the Nifty 500, Kalyan Jewellers gained 18%, while Page Industries fell 13%. Foreign institutional investors bought roughly ₹33,300 crore of equities on a net basis, more than offsetting domestic institutional selling and supporting the benchmarks.
Global equities mostly rose, with Taiwan, Japan and South Korea leading gains in Asia, while Hong Kong and Malaysia declined. The S&P 500 gained 2.5%, although US technology stocks came under renewed pressure late in the week as investors weighed elevated valuations and the prospective returns on AI investment. Persistent US inflation and hawkish Federal Reserve commentary lifted Treasury yields and strengthened the dollar, keeping financial conditions tight despite the equity rebound.
Brent ended near $96 a barrel, up about 3.5% on the week, with geopolitical tensions keeping supply risks in focus. India’s October retail inflation rose to 6.1%, while the rupee weakened to around ₹94.2 per dollar. Higher inflation limits the RBI’s room to ease. For companies that rely on imported inputs, elevated crude prices and a weaker rupee could put margins under pressure, particularly where pricing power is limited.
Q2FY27 results provided a stronger domestic earnings backdrop. Nifty 50 profit after tax rose 24.3% YoY versus 20.6% expected by street. Excluding both Tata Motors and Oil & Gas, profit still grew 18.5% versus 14.9% expected, with 41 of 50 constituents reporting higher profits. First-half profit growth of 18.3%, following two financial years of single-digit growth, points to a turn in the earnings cycle.
Metals & Mining, Industrials and PSU Banks delivered some of the strongest earnings beats, while Internet, Infrastructure and Utilities fell short of expectations. Consensus projects 15.1% FY27 profit growth, and the Nifty 50 trades at roughly 21x FY27 and 18x FY28 consensus earnings. At these valuations, the next test is whether stronger results lead to upgrades in forward estimates. Management commentary on demand, pricing and input costs will help gauge how much of the first-half momentum can carry into the second half.
A sustained market advance will depend on earnings delivery, margin resilience and whether foreign buying persists. Continued inflows could help broaden participation beyond the sectors that led this week. A renewed rise in crude or US yields could weigh on the rupee and limit the scope for valuations to move higher.
The full Weekly Flash, with sector, stock, global and commodity tables, is available as a PDF below.